
The bank where you’ve built your savings for a decade might be the least effective partner for your next UAE property investment. It’s a common assumption that loyalty earns you the best rate, but in a market where the 3-Month EIBOR has declined from 4.3% in mid-2025 to 3.6% in March 2026, that assumption can be expensive. You likely feel the weight of overwhelming fine print and the anxiety of hidden valuation costs. I understand that the search for clarity feels endless when you’re facing strict criteria as a self-employed investor or a non-resident.
This guide clarifies the essential choice between a mortgage broker vs bank Dubai so you can secure the most advantageous financing possible. We’ll explore how to navigate current LTV limits, minimize processing fees, and engineer a debt burden ratio that protects your long-term wealth. From identifying the lowest interest rates to streamlining your approval with minimal paperwork, you’re about to transform a complex transaction into a strategic victory. If you choose the right path, then your mortgage becomes a tool for growth rather than a source of stress.
Key Takeaways
- Distinguish between a bank’s rigid product menu and a broker’s solution-oriented approach. Identifying the right partner ensures your financial profile is matched with the institution most likely to favor your application.
- Analyze the total cost of borrowing by comparing a mortgage broker vs bank Dubai beyond the headline interest rate. Hidden benefits like valuation waivers and flexible pre-payment terms often provide the greatest long-term value.
- Navigate the 2026 UAE Central Bank LTV regulations with expert precision. Understanding these limits allows you to maximize your leverage while protecting the liquidity of your property portfolio.
- Discover the strategic advantage of integrated mortgage lending services. Combining financial guidance with real estate expertise eliminates communication gaps and creates a seamless transition from selection to settlement.
The UAE Financing Dilemma: Navigating the Choice Between Banks and Brokers
The UAE property market is a high-stakes arena where strategic leverage defines the line between a simple purchase and a high-performing investment. In 2026, with citywide residential capital values projected to rise by 10%, the cost of a sub-optimal mortgage is higher than ever. When debating the merits of a mortgage broker vs bank Dubai, you must look beyond the immediate interest rate. Banks represent a single source of capital with rigid, proprietary products. Brokers, conversely, act as independent conduits to the entire national lending ecosystem. Your choice impacts more than your monthly payment; it determines your future liquidity and your ability to scale your property portfolio.
The Direct Bank Approach: Traditional and Linear
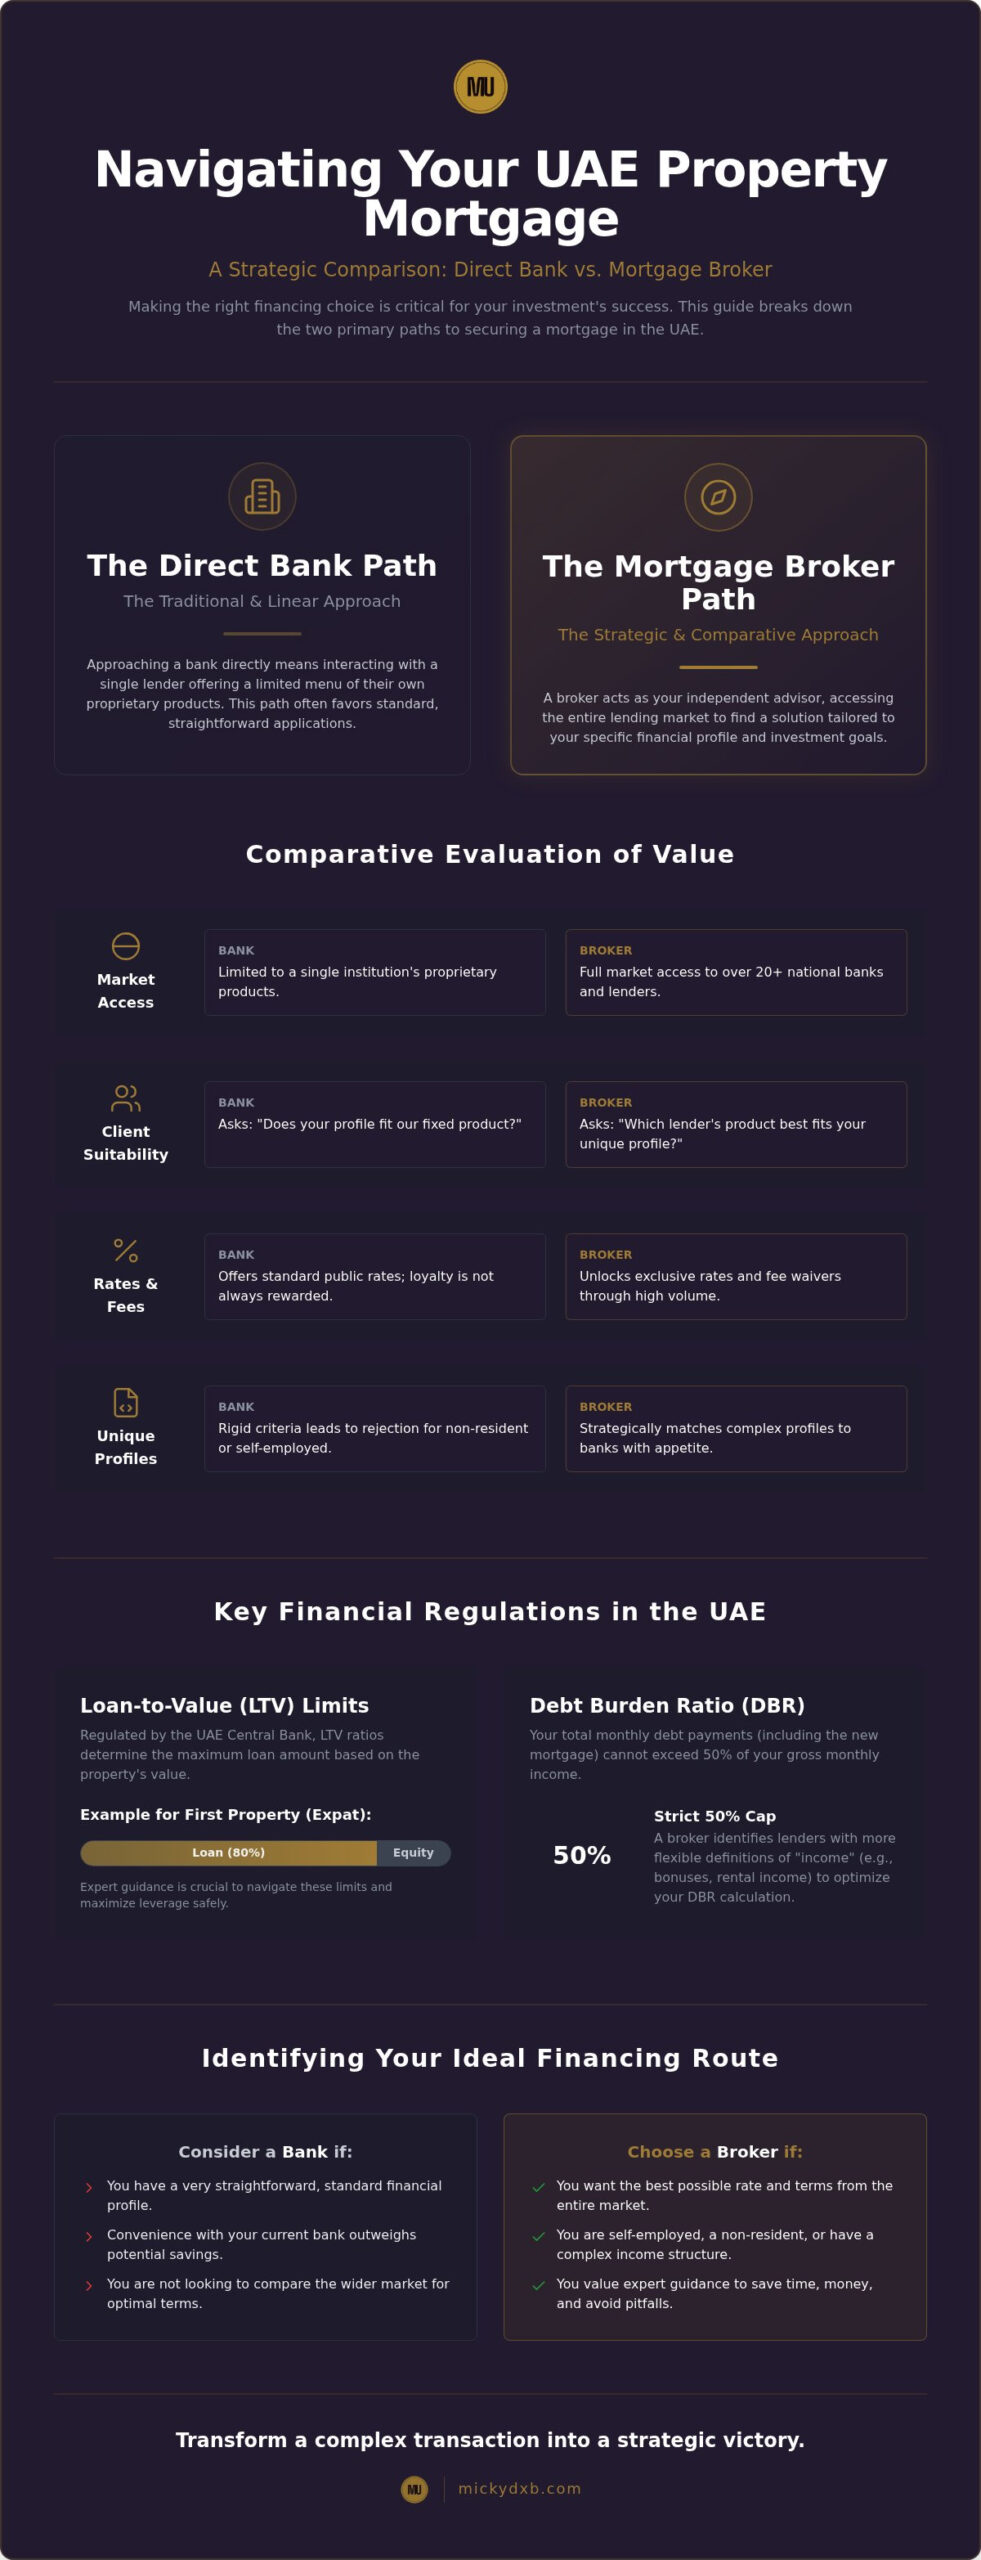
Banks prioritize their internal risk appetite over your unique financial narrative. They operate with a “Fixed Product” menu. If your profile as a self-employed investor or a non-resident doesn’t fit their specific box, then the application is often rejected without recourse. Many investors fall into the “loyalty trap,” assuming their primary bank will reward years of history with a discounted rate. In reality, the most competitive offers are frequently reserved for new customer acquisition. If you limit yourself to your existing bank, then you’re essentially ignoring the terms offered by the rest of the market. This linear path is often slower and less flexible, as the bank’s only goal is to sell its own proprietary debt.
The Independent Broker Model: Strategic and Comparative
A broker operates as a sophisticated market aggregator, providing a bridge to 20+ national banks. To understand the structural advantage of this role, it helps to ask: What is a Mortgage Broker? In the Dubai context, they’re strategists who match your specific profile to the lender that currently has the highest appetite for your criteria. They don’t just find a product; they pre-qualify your documents to prevent unnecessary credit hits that could damage your standing.
Brokers leverage massive transaction volumes to unlock exclusive rates and valuation waivers that aren’t available to the general public. This transition from a single-product search to a market-wide strategy ensures you aren’t just getting a loan. You’re securing a partnership that prioritizes your long-term wealth. From initial document review to the final registration at the Dubai Land Department, the broker manages the friction. This model provides the clarity, speed, and exclusivity required for the 2026 market. If you want a tailored financial strategy rather than a generic product, then the independent route is your natural path.
Internal Mechanics: How Banks and Brokers Source Property Finance
Banks are essentially product manufacturers. They design a specific financial instrument and look for borrowers who fit the exact specifications of that design. If your profile deviates even slightly from their internal model, then the underwriting software triggers an automatic rejection. This is the fundamental reality of the mortgage broker vs bank Dubai choice. While a bank offers the comfort of a known brand, it lacks the agility to adjust for your unique investment journey. A broker, however, operates as a solution-first strategist. They don’t have a product to sell; they have a network to navigate.
The Central Bank of the UAE maintains strict guardrails to ensure market stability, including a Debt Burden Ratio (DBR) capped at 50% of your gross monthly income. While a bank will simply apply this rule to their internal products, a broker analyzes how different lenders calculate “income.” Some banks are more flexible with rental income or bonuses, while others remain rigid. This distinction is where the choice between “Convenience vs. Optimization” becomes clear. You can choose the convenience of your local branch, or the optimization of a tailored financial strategy.
Underwriting and Appetite: The Invisible Filter
Lending criteria are not static. Banks frequently adjust their exposure to certain sectors or demographics based on their monthly targets. One month, a bank might be aggressive in seeking non-resident investors; the next, they may tighten their requirements significantly to balance their portfolio. Brokers maintain constant communication with credit departments to identify which institutions are currently “hungry” for business. This insider perspective is vital for self-employed applicants whose income documentation requires a more nuanced interpretation than a standard salary certificate. If you want to avoid the sting of an unexpected rejection, then knowing the lender’s current appetite is essential.
Compliance and Documentation Support
The administrative burden of a UAE mortgage can be daunting. A broker provides a “one-and-done” submission process. Instead of you managing multiple threads with different underwriters, the broker acts as a single point of contact who understands the specific “language” each bank requires. This prevents application fatigue and ensures your file is presented in the most favorable light. If you’re looking for a partnership-oriented approach to financing, then having an advisor who manages the back-and-forth is indispensable.
By calculating your DBR and pre-verifying your LTV—which remains at 80% for expats on properties under AED 5 million—the broker ensures that by the time a bank sees your file, the path to approval is already paved. This meticulous preparation turns a stressful compliance exercise into a streamlined success story. It’s about moving from a position of uncertainty to one of strategic advancement.
Broker vs Bank Dubai: A Comparative Evaluation of Value
A headline interest rate is often a distraction from the true cost of property ownership. While a bank might lure you with a 3.75% fixed rate, the long-term financial health of your investment depends on the clauses hidden in the fine print. This comparison of a mortgage broker vs bank Dubai reveals that the cheapest rate on paper frequently becomes the most expensive loan over a five-year horizon due to rigid exit fees and mandatory insurance markups. A broker delivers value through three distinct pillars: choice across the entire market, technical expertise in structuring the deal, and the leverage to negotiate terms you couldn’t access alone. They look beyond the initial transaction to ensure your mortgage remains a flexible asset rather than a restrictive liability.
Rate Comparison and Product Diversity
Fixed rates for 1-2 year terms currently start from 3.75%, while variable rates typically track the 3-Month EIBOR plus a margin. Since the 3-Month EIBOR has declined from 4.3% in mid-2025 to 3.6% in March 2026, the timing of your switch to a variable rate is a critical strategic decision. Brokers help you hedge against future volatility by providing access to products that aren’t advertised to the public. Exclusive products are pre-negotiated tranches of funding available only through specific intermediaries who move high volumes of business. These deals often include lower margins or extended fixed periods that provide the stability required for a growing property portfolio.
Fee Structures and Transparency
Standard bank processing fees typically sit at 1% of the loan amount, but the real “value leak” often occurs in property valuation fees and life insurance. Valuation costs in 2026 range between AED 2,500 and AED 3,500 plus VAT. Many banks mandate their own in-house life insurance, which can be significantly more expensive than an external policy. A broker identifies these hidden costs early, often negotiating valuation waivers or sourcing cheaper external insurance providers to protect your monthly cash flow.
The decision ultimately rests on your investment horizon and liquidity needs. If you prioritize upfront cost, then a direct bank deal with subsidized entry fees might seem attractive; if you prioritize long-term ROI, then a broker-negotiated deal with external life insurance and flexible pre-payment terms is the superior strategic choice. By choosing the latter, you ensure that your capital isn’t trapped by restrictive clauses when the market presents new opportunities for advancement. Planning your eventual exit is equally important, and understanding how to sell an apartment in Dubai at peak value ensures your financing strategy aligns with your long-term wealth goals.
Strategic Selection: Identifying Your Ideal Financing Route
Choosing the right financing route is a matter of matching your financial profile to the market’s current appetite. In 2026, the choice between a mortgage broker vs bank Dubai depends largely on whether you require a simple loan or a complex financial architecture. Your residency status and the intended Loan-to-Value (LTV) ratio are the primary variables in this decision. For expatriates, the LTV is capped at 80% for first homes under AED 5 million, while UAE nationals can access up to 85%. If you understand these limits early, then you can negotiate from a position of strength rather than desperation. Securing a mortgage pre-approval is the most critical step before entering any property negotiation. It transforms you into a “cash-ready” buyer, often allowing for more aggressive price discussions with sellers.
Profile 1: The First-Time Homebuyer
For those new to the UAE market, professional guidance is often more valuable than a marginal difference in interest rates. The journey from a pre-approval letter to the final No Objection Certificate (NOC) from the developer is filled with technical hurdles that can derail a transaction. A broker manages these friction points, ensuring that the valuation, the offer letter, and the final transfer at the Dubai Land Department align perfectly. If you want a comprehensive roadmap for your first purchase, then exploring a detailed guide on property financing Dubai is a vital starting point. This profile benefits most from the mentorship a broker provides, as it prevents costly mistakes during the “post-approval” phase when most delays occur.
Profile 2: The Portfolio Investor
Seasoned investors look beyond the first transaction to see the larger narrative of their financial journey. When evaluating a mortgage broker vs bank Dubai, the portfolio investor prioritizes the ability to manage multiple loans simultaneously. Managing a growing collection of assets requires a sophisticated “Equity Release” strategy to fund new acquisitions without depleting cash reserves. Brokers facilitate cross-bank lending, strategically placing different properties with different lenders to maximize Debt-to-Burden Ratio (DBR) limits. This approach allows you to scale your holdings while maintaining the flexibility to exit when the market peaks. If your goal is a high-value exit, then understanding property resale Dubai strategies is essential to timing your leverage correctly. A comprehensive checklist on how to sell an apartment in Dubai can further sharpen your exit strategy and ensure you capture maximum capital appreciation at the right moment.
To ensure your financing is as strategic as your property selection, consult with a mortgage advisor who understands the nuances of the 2026 market. By aligning your selection, leverage, and timing, you transform a standard mortgage into a powerful engine for wealth creation. Whether you’re weighing the steady rental income of a buy-to-let asset or the capital gains potential of an off-plan vs ready property investment Dubai strategy, your mortgage structure must reflect your ultimate investment objective.
The Micky Uppal Advantage: Integrated Finance and Real Estate Consulting
The traditional real estate model is often fragmented; you find a property with one agent and then battle for financing with a separate institution. This disconnect creates a dangerous communication gap between the seller, the agent, and the lender. When you evaluate the choice of a mortgage broker vs bank Dubai, the most sophisticated path is an integrated approach where your real estate consultant and mortgage advisor operate under one roof. This synergy ensures that the property’s valuation aligns with the bank’s appetite before you sign the initial agreement. It’s a fundamental shift from a transactional mindset to a partnership-oriented journey that prioritizes your long-term security.
If you align your financing with your acquisition strategy, then your portfolio gains the resilience needed for long-term growth. We don’t just secure a loan; we engineer a financial foundation for your property investments. From the initial search to the final registration at the Dubai Land Department, every step is managed to eliminate the “post-approval” friction that often stalls transactions. We prioritize choice, expertise, and negotiation to ensure your capital is always working for your advancement.
A Decade of Market Intelligence
Experience is the only true hedge against market volatility. With over 10 years of UAE market experience and 2,000+ successful listings, we understand the nuances of property valuations from the bank’s perspective. This depth of intelligence translates into faster approvals and smoother exits because we know which properties will trigger red flags for underwriters. We provide an unwavering reliability that only a seasoned guide can offer. Our integrated mortgage lending services are designed to streamline the entire transaction process, ensuring that your financial profile and your property selection are in perfect harmony.
Securing Your Future: The Next Steps
The transition from discovery to strategic advancement begins with a single, low-friction conversation. We invite you to a personalized financial consultation where we move beyond generic products to create a bespoke roadmap for your property journey. This is your opportunity to gain clarity on the total cost of borrowing and to understand how to maximize your leverage in the 2026 market. Choosing the right path today provides the security and satisfaction that come from a well-informed choice. If you’re ready to secure the most advantageous financing for your UAE property investment, then consult with a trusted advisor to begin your partnership-oriented journey.
Strategic Advancement for Your UAE Property Journey
Your property investment is a significant milestone that requires more than just a standard loan. It demands a financial strategy that evolves alongside the market. We’ve explored the critical differences between a mortgage broker vs bank Dubai, highlighting that while a bank offers a single product, a broker provides a gateway to the entire lending ecosystem. By optimizing your interest rates and navigating the 2026 LTV regulations, you ensure your capital remains flexible for future opportunities. Success in this high-stakes market depends on a partnership that bridges the gap between real estate selection and financial execution.
With over 10 years of UAE real estate expertise and a track record of 2,000+ successful listings, I provide the integrated mortgage and investment consulting necessary for a seamless transaction. You don’t have to navigate the fine print alone. Secure your strategic mortgage pre-approval with Micky Uppal today to transform your investment vision into a secure reality. The right choice today builds the foundation for a prosperous and stable property portfolio. Take the next step toward a well-informed and rewarding future.
Frequently Asked Questions
Is it cheaper to go to a bank directly than using a mortgage broker in Dubai?
It’s a common misconception that direct bank applications are cheaper. While you avoid a broker fee, you often miss out on exclusive interest rate tranches and negotiated waivers on valuation or processing fees. When comparing a mortgage broker vs bank Dubai, the broker’s ability to source external life insurance can save you thousands over the loan term. They identify the most cost-effective total package rather than just a headline rate.
Can a mortgage broker help if my bank has already rejected my application?
A rejection from your primary bank is not the end of your property journey. Banks often decline applications based on their current monthly exposure to specific sectors or residency statuses. A broker analyzes the rejection reason and redirects your file to a lender that currently has a high appetite for your specific profile. They understand the invisible filters that vary between institutions, ensuring your next submission is strategically optimized for success.
What are the typical fees associated with a mortgage broker in the UAE?
In the UAE market, banks typically charge a processing fee of 1% of the loan amount. Brokers may charge a separate success fee for their consultancy and negotiation services. However, a seasoned guide often secures savings that outweigh these costs, such as lower interest margins or the removal of bank-mandated insurance markups. This ensures the total cost of borrowing remains lower than a standard retail application.
Do I need a mortgage pre-approval before I start looking at properties?
Securing a mortgage pre-approval is the most critical first step before you begin your property search. It establishes your exact budget and proves to sellers that you have the financial backing to complete the transaction. In a competitive market, a pre-approval letter gives you the leverage to negotiate more aggressive price discounts. It transforms you from a casual browser into a serious, strategic investor ready for advancement.
Can I get a mortgage in the UAE if I am a non-resident or an expat?
The UAE mortgage market is highly accessible for both expatriates and non-residents. Expatriates can secure a Loan-to-Value (LTV) of up to 80% for their first home under AED 5 million. Non-residents generally face more conservative limits, often requiring a 50% down payment. A broker is essential here to navigate the specific documentation requirements and to identify which national banks are currently favoring international investors.
How long does the mortgage approval process take through a broker vs a bank?
A direct bank application can often take two weeks or more due to internal administrative layers. Brokers typically secure pre-approvals within 3 to 5 working days because they pre-vet your documents and submit them directly to the right underwriters. This efficiency is vital when you find a high-value property that requires a fast commitment. If you choose a broker, then you’re prioritizing speed and accuracy over a slow, linear process.
Are mortgage brokers in Dubai regulated by the Central Bank?
Every entity providing mortgage lending services in the UAE must adhere to the strict regulations set by the Central Bank. This includes compliance with the 50% Debt Burden Ratio (DBR) and specific LTV caps for different buyer profiles. Working with a licensed professional ensures that your financing is structured legally and ethically. It provides a foundation of trust and transparency that is essential for high-stakes financial decisions.
Can a broker help me with equity release on an existing property?
Equity release is a powerful tool for portfolio growth that a broker can certainly facilitate. If your property has appreciated in value or you have paid down a significant portion of the principal, then you can unlock that capital for new acquisitions. A broker compares different lenders to find the one offering the most flexible terms for refinancing. This strategy allows you to scale your investments without depleting your personal cash reserves.

Leave a Reply